The Process
How a Private Pension Strategy Works
From your first conversation to a fully deployed, IRS-compliant private pension — here is exactly what the process looks like, and what you can expect at every stage.
Discovery & Assessment
We Start by Understanding Your Full Financial Picture
Every private pension strategy begins with a thorough discovery process. We review your income, business structure, tax situation, existing retirement accounts, and long-term goals.
This is not a sales call. It is a genuine assessment to determine whether a private pension is the right fit for you — and if so, how powerful the outcome could be. We will tell you honestly if it is not the right strategy.
Most clients discover they have been leaving significant tax-free wealth on the table for years. The discovery session makes that clear.
What This Includes
Review of current income and tax liability
Analysis of existing retirement accounts
Assessment of business structure and eligibility
Projection of potential tax-free retirement wealth
Custom Strategy Design
Your Private Pension Is Built Around You — Not a Template
Once we confirm that a private pension is the right fit, we design your strategy from the ground up. This is not an off-the-shelf product. Every element — contribution structure, investment allocation, distribution planning, and legal documentation — is tailored to your specific situation.
We work with you to determine the optimal contribution level, the most advantageous structure for your business, and the distribution strategy that will deliver the greatest tax-free income in retirement, and/or the greatest up front deferral, up to $300k annually, or more!
The design phase typically takes two to three weeks and results in a complete, IRS-compliant private pension plan ready for implementation.
What This Includes
Custom contribution structure maximizing tax advantages
Investment allocation aligned with your timeline and risk profile
Distribution strategy for maximum tax-free retirement income
Full IRS-compliant documentation and plan design
Implementation & Deployment
We Handle Everything. You Focus on Your Business.
Implementation is where most financial strategies fall apart — buried in paperwork, IRS filings, and administrative complexity. We handle all of it.
Our team manages every aspect of the deployment: IRS filings, trust documentation, account establishment, and initial funding. We coordinate with your existing CPA or attorney as needed, and we provide clear documentation of every step.
From the moment you approve the strategy to the day your pension is fully operational, you will have a dedicated point of contact and complete transparency into the process.
What This Includes
Complete IRS filing and compliance management
Trust and legal documentation handled end-to-end
Coordination with your existing CPA and legal team
Dedicated point of contact throughout implementation
Ongoing Management & Optimization
A Strategy That Grows With You for Decades
A private pension is not a set-it-and-forget-it product. Tax laws change. Your income changes. Your retirement timeline evolves. We stay actively engaged to ensure your strategy continues to perform at its highest potential.
We conduct annual reviews of your pension structure, contribution levels, and investment performance. When tax law changes create new opportunities — or new risks — we proactively reach out with recommendations.
Our clients do not just get a pension. They get a long-term financial partner who is invested in their outcome.
What This Includes
Annual strategy review and optimization
Proactive tax law monitoring and updates
Contribution level adjustments as income changes
Ongoing access to your dedicated advisor
The Tax Advantages
Why Private Pensions Outperform Every Alternative
Tax-Free Growth
Your contributions grow inside the pension without annual taxation — no capital gains, no dividend taxes, no drag on compounding.
Tax-Free Distributions
When structured correctly, distributions in retirement come out completely free of federal income tax — unlike 401(k) and IRA withdrawals.
Contribution Deductions
Contributions to your private pension are typically tax-deductible as a business expense, reducing your taxable income in the years you contribute.
No RMD Requirements
Unlike IRAs and 401(k)s, some private pensions can be structured without Required Minimum Distributions — giving you full control over your retirement income timing.
Asset Protection
Pension assets are generally shielded from creditors and legal judgments, protecting your retirement wealth from business risk.
Estate Transfer Advantages
Private pensions can be structured to pass wealth to heirs with favorable tax treatment, making them a powerful legacy planning tool.
The Hidden Math Problem
Your Average Return Is Not Your Actual Return
Most investors are told their portfolio averaged a strong return over time. What they are not told is that average returns and actual returns are two very different numbers — and the gap between them can cost you decades of wealth.
The chart illustrates this clearly: a portfolio that gains 40%, loses 40%, gains 20%, loses 30%, and gains 30% has an average return of +20% — yet the actual ending balance reflects a −8.3% real return. Any year with a loss permanently damages compounding.
Private pensions structured with downside protection eliminate this problem entirely. When your floor is zero — meaning you never participate in market losses — your average return and your actual return stay aligned. That is the compounding advantage that changes retirement outcomes.
The private pension advantage: Strategies that credit market-linked gains while protecting against losses mean your money never goes backward — and compounding works the way it was always supposed to.
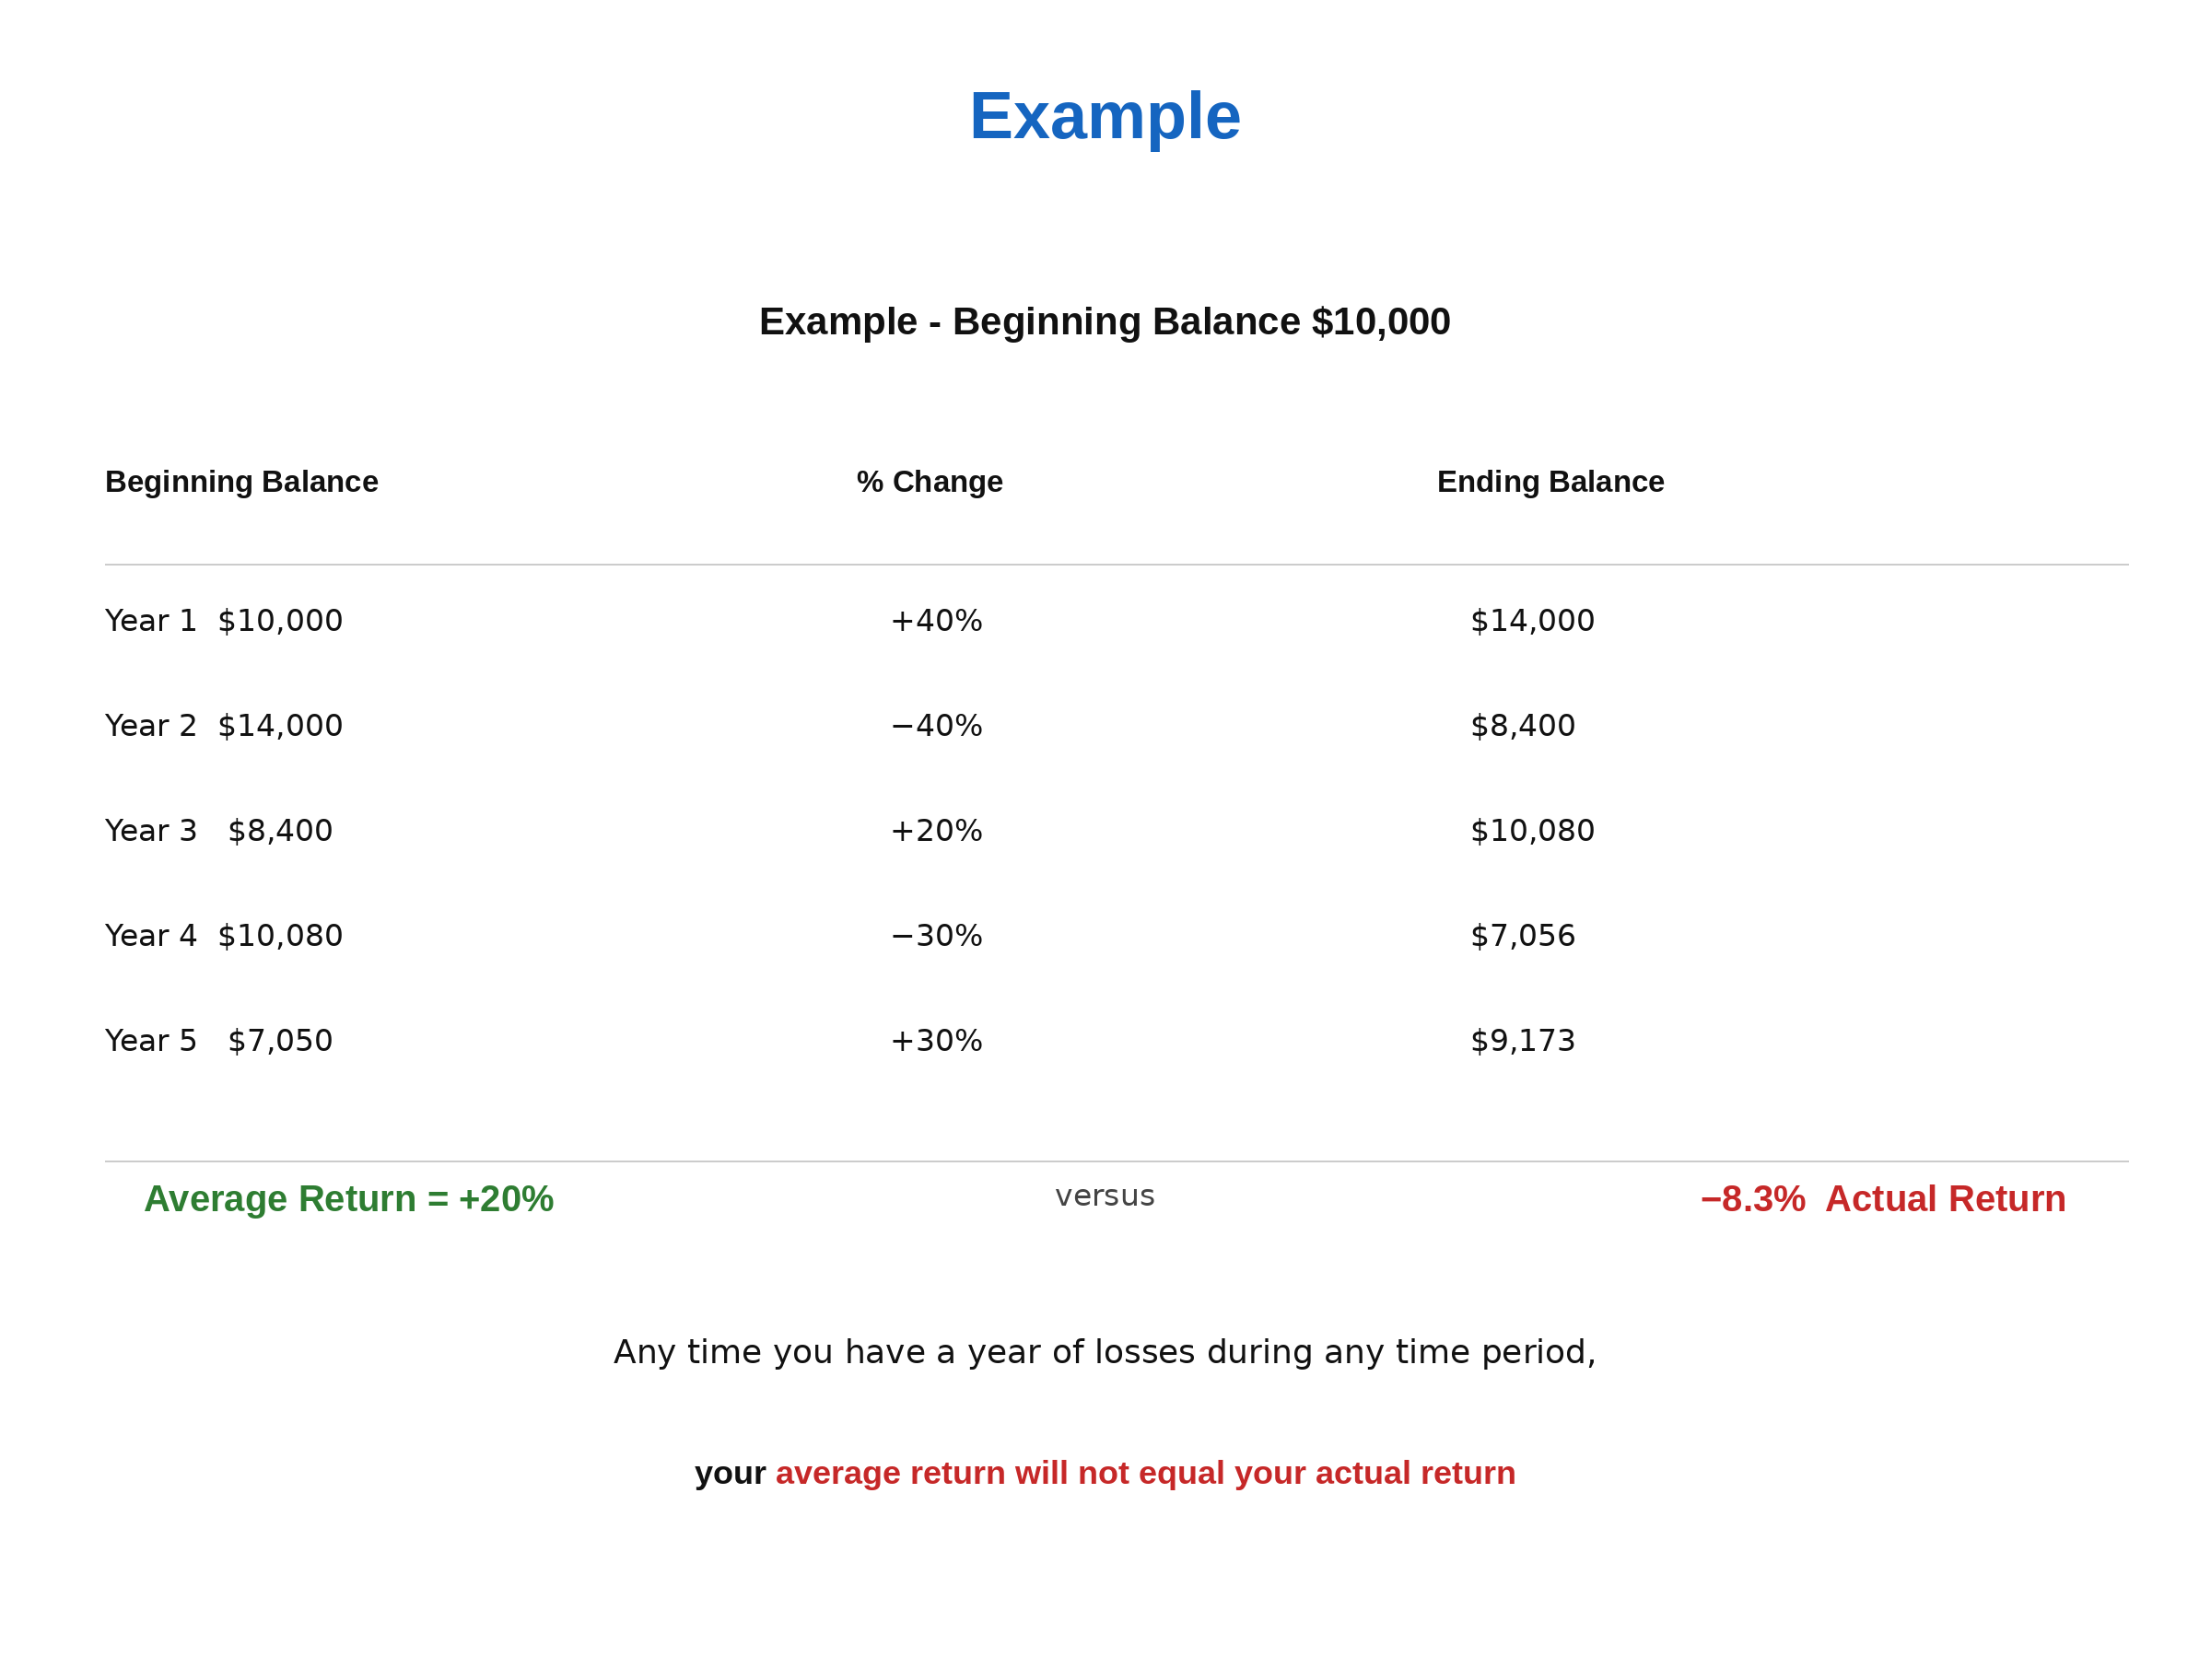
Example only. For illustrative purposes. Past performance does not guarantee future results.
Side by Side
Private Pension vs. Traditional Retirement Accounts
| Feature | Private Pension | 401(k) / IRA |
|---|---|---|
| Tax-Free Growth | ✓ Yes | ✗ Taxed annually (traditional) |
| Tax-Free Distributions | ✓ Yes, when structured correctly | ✗ Taxed as ordinary income (traditional) |
| Annual Contribution Limit | ✓ Significantly higher | ✗ $23,000 / $7,000 (2024) |
| Required Minimum Distributions | ✓ Not required | ✗ Required at age 73 |
| Asset Protection | ✓ Generally shielded from creditors | ~ Varies by state |
| Customization | ✓ Fully tailored to your situation | ✗ Standardized products |
| Estate Planning Advantages | ✓ Favorable legacy transfer options | ~ Limited |
| Employer Requirement | ✓ Self-employed / business owners eligible | ~ Varies |
Historical Proof
Zero Is Your Hero
This 10-year historical lookback tells the story clearly. Starting with the same $100,000 in 1998, the S&P 500 Index delivered a −29.83% real return over the decade — ending at just $77,021 after the 2008 crash wiped out years of gains.
The Indexed Product — which participates in market gains but is protected from losses — delivered a +74.19% real return over the same period, ending at $174,187. Same market. Same decade. Dramatically different outcome.
The difference is the zero floor. In years like 2000, 2001, 2002, and 2008 — when the S&P 500 lost double digits — the Indexed Product credited 0%. No loss. No recovery needed. Compounding continued uninterrupted.
−29.83%
S&P 500 Real Return
+74.19%
Indexed Product Real Return
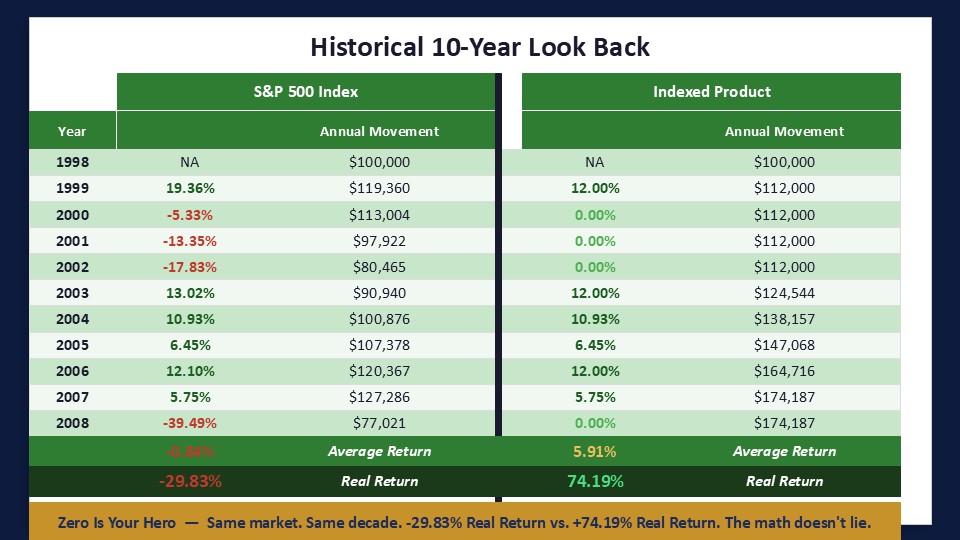
Historical illustration only. Past performance does not guarantee future results.

Our Commitment
Transparency at Every Step
We believe you should understand exactly what you own, why it works, and what it costs. There are no hidden fees, no opaque structures, and no pressure to move forward before you are ready.
Every client receives a complete written explanation of their strategy before implementation begins. We welcome questions — and we take the time to answer them fully.
If a private pension is not the right fit for your situation, we will tell you. Our reputation is built on doing right by our clients — not on closing transactions.
Ready to Begin?
The First Step Takes Either 5 Minutes, or 15 Minutes On A ZOOM Meeting
A complimentary discovery call is all it takes to find out whether a private pension strategy is right for you — and how much you stand to gain. No obligation, no pressure, no sales pitch.